The marketer at an analytics reporting service requests 700,000 ₸ for a new launch: 600,000 ₸ advertising and 100,000 ₸ preparation. The finance lead opens last month's figures: 1,200,000 ₸ revenue and a 200,000 ₸ result before tax. "You are asking for more than three months of that result. What will we get, and when will the money return?" A table of cheap leads cannot answer that.
In the service model, 20 companies paid for and received a monthly package at 60,000 ₸ each. Variable fulfilment costs 20,000 ₸ per company, leaving 40,000 ₸ contribution. The figures are made up. Last month is treated as an actual result within the example; the new launch and its payments are still scenarios.
Establish the starting result
Revenue of 1,200,000 ₸ minus 400,000 ₸ fulfilment leaves 800,000 ₸ contribution. After 200,000 ₸ advertising and 400,000 ₸ other fixed expenses, 200,000 ₸ remains before tax. Fixed expenses cover marketing, sales and management pay, premises and shared services. Advertising and variable client work are already counted separately.
Contribution is revenue minus variable costs, as described in ACCA's article. The cost categories matter to the decision. Work paid for each connected client belongs in the variable row. Fixed team pay stays separate until the new volume requires it to increase.
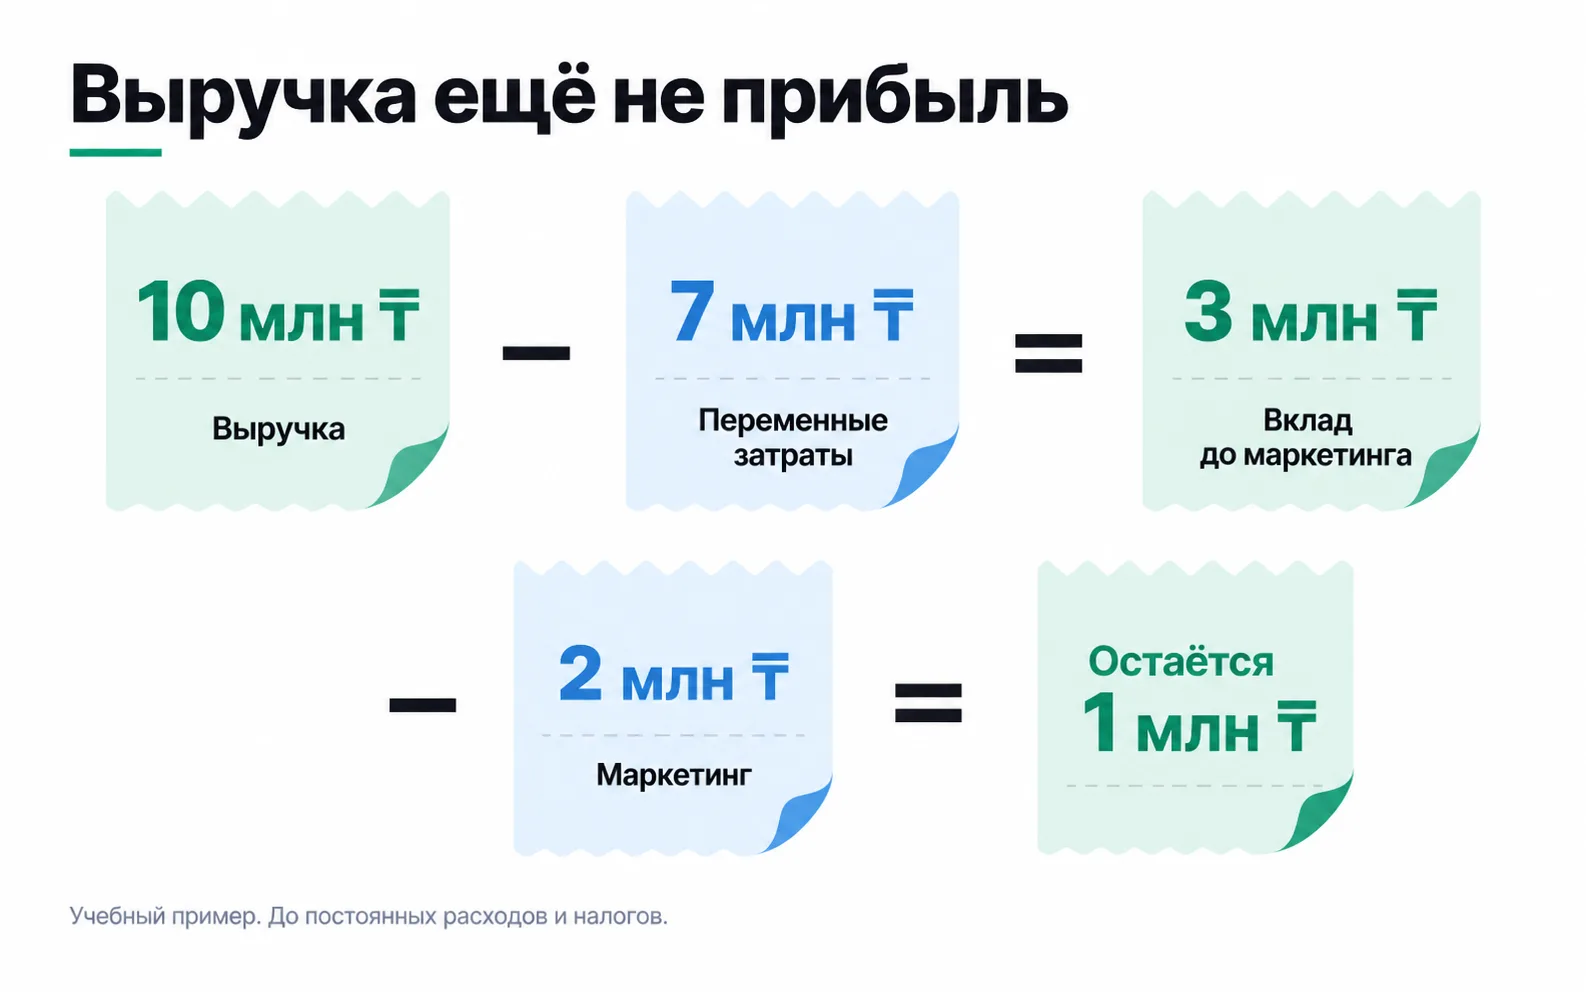
The image uses a different example with a 30% contribution rate: 10 million ₸ revenue minus 7 million ₸ variable costs and 2 million ₸ marketing leaves 1 million ₸. Do not transfer that rate to our service, whose standard package contributes 40,000 ₸ from 60,000 ₸ revenue.
Define the baseline for the new budget
The launch is compared not with zero but with what would have happened without it. The baseline continues normal operations: existing advertising, sales and service. The new launch gets its own 700,000 ₸ and needs to add clients beyond that plan. Counting every payment after launch would include people who would have arrived without it.
For the calculation, assume the extra volume fits current capacity. Variable fulfilment remains 20,000 ₸ per client, and fixed expenses do not change. These are model assumptions. The delivery lead must assess them before approval: a new hire, separate licence or additional shift creates another row.
The 700,000 ₸ already includes 100,000 ₸ preparation. Do not add it again to fulfilment or the overall marketing row when calculating the initiative's result. The original 200,000 ₸ of normal advertising stays in the baseline. Finance can then combine baseline and incremental calculations into the full P&L without duplicate deductions.
Three first-month scenarios
The table covers only the first paid and delivered month for new clients. No scenario probabilities are assigned. Here we assume that all these clients came because of the launch; that will have to be checked after it runs.
| Scenario | Additional new clients | Revenue | Fulfilment | Contribution | After 700,000 ₸ launch costs |
|---|---|---|---|---|---|
| Unfavourable | 10 | 600,000 ₸ | 200,000 ₸ | 400,000 ₸ | -300,000 ₸ |
| Base | 20 | 1,200,000 ₸ | 400,000 ₸ | 800,000 ₸ | 100,000 ₸ |
| Favourable | 30 | 1,800,000 ₸ | 600,000 ₸ | 1,200,000 ₸ | 500,000 ₸ |
At 40,000 ₸ contribution, 18 additional clients cover launch costs in their first month: 700,000 / 40,000 = 17.5, rounded up to a whole client. Eighteen contribute 720,000 ₸, leaving just 20,000 ₸. This is a model threshold, not a sales forecast or permission to spend without other evidence.
The base scenario has 100,000 ₸ of headroom. Another 100,000 ₸ in fixed costs for the extra volume would consume it all. If variable fulfilment rises to 25,000 ₸, contribution falls to 35,000 ₸ per client and twenty clients produce exactly 700,000 ₸. This reveals which assumptions matter most to the decision.
Where the forecast comes from
Every number in the request needs a basis. Support audience size with your own list or observed demand. Use comparable cohorts with the same offer for the qualified-enquiry rate. Take time to payment from the CRM. Have the people doing the work estimate fulfilment costs.
Past average client cost is a starting point, but a new budget may buy different demand. In the original month, 200,000 ₸ advertising brought ten new clients. Another 600,000 ₸ media budget need not bring thirty more: traffic, audience and contact frequency will change. Explain the ten, twenty and thirty in the scenarios instead of stretching last month's row with a formula.
Check that assumptions work together. If the sales forecast depends on a discount, the 60,000 ₸ price no longer belongs in the table. If clients from another city need costlier support, the old 20,000 ₸ fulfilment assumption also needs revision. Scenarios help when they expose these connections.
Attribution and incremental effect
UTM tags and the CRM show which enquiries are connected to the launch and reach payment. But a buyer may already know the service and intend to contact it directly. Attributed revenue distributes sales under a rule; launch effect asks what changed because of the launch.
If the decision requires an effect estimate, select a suitable control comparison or another justified method before starting. It needs a unit, schedule, sample size and stated limits, as in HADI. If volume is too low for the required precision, preserve that uncertainty in the report. Twenty attributed payments cannot become twenty incremental payments merely to match the base plan.
Infrastructure work needs a different acceptance method. Reconciling missing payments, for example, may improve reporting without new sales. Research may produce a decision to reject an expensive integration. The budget still has a task, costs, timing and completion criterion; it does not need an invented weekly ROAS.
When cash is needed
The base scenario's positive 100,000 ₸ remainder arrives after twenty clients have received the service and paid. Suppose the 700,000 ₸ launch cost is paid upfront, then 400,000 ₸ is spent on fulfilment, and clients pay 1,200,000 ₸ only after delivery. Until those receipts arrive, additional cash required reaches 1,100,000 ₸.
| Point in the illustrative schedule | Initiative cash movement | Cumulative balance from zero |
|---|---|---|
| Advertising and preparation paid | -700,000 ₸ | -700,000 ₸ |
| Fulfilment paid | -400,000 ₸ | -1,100,000 ₸ |
| Client payments received | 1,200,000 ₸ | 100,000 ₸ |
This schedule covers only the additional launch. Existing company commitments sit alongside it in the overall cash plan. Prepayments or costs spread over time would change the maximum gap. Finance therefore needs timing, not just the final profit figure.
Conditions for releasing the next part
The request states what is enough to continue: data is collected correctly, the offer can be delivered, the audience fits the task, and expenses remain within agreed limits. When to look at payments depends on how long the deal takes. Before that, leads help find failures but cannot replace clients' first-month results.
Separate stopping for harm, errors or unavailable delivery from declaring an experiment winner. If a payment cannot be connected to its variant or a manager promises a nonexistent feature, resolve the problem first. Preparation money already spent does not justify further spending that no longer serves the objective.
Exercise: a last-minute discount
Build a request for one initiative: amount, breakdown, baseline without it, three contribution scenarios, cash schedule, owner and continuation conditions. Then recalculate the service's base scenario if all twenty new clients get a 10% discount while fulfilment and budget stay unchanged.
The price becomes 54,000 ₸ and client contribution 34,000 ₸. Twenty clients produce 680,000 ₸ contribution, leaving negative 20,000 ₸ after the 700,000 ₸ launch cost. Covering it needs 21 incremental clients: 21 × 34,000 = 714,000 ₸, leaving 14,000 ₸. The price already includes the discount, so do not deduct it again. The team now needs to explain why the discount will add enough clients or revise the launch.
Show repeat months separately. Until continuation happens, they remain a future-contribution scenario; they enter actual results after payment and service delivery under the company's financial reporting method.