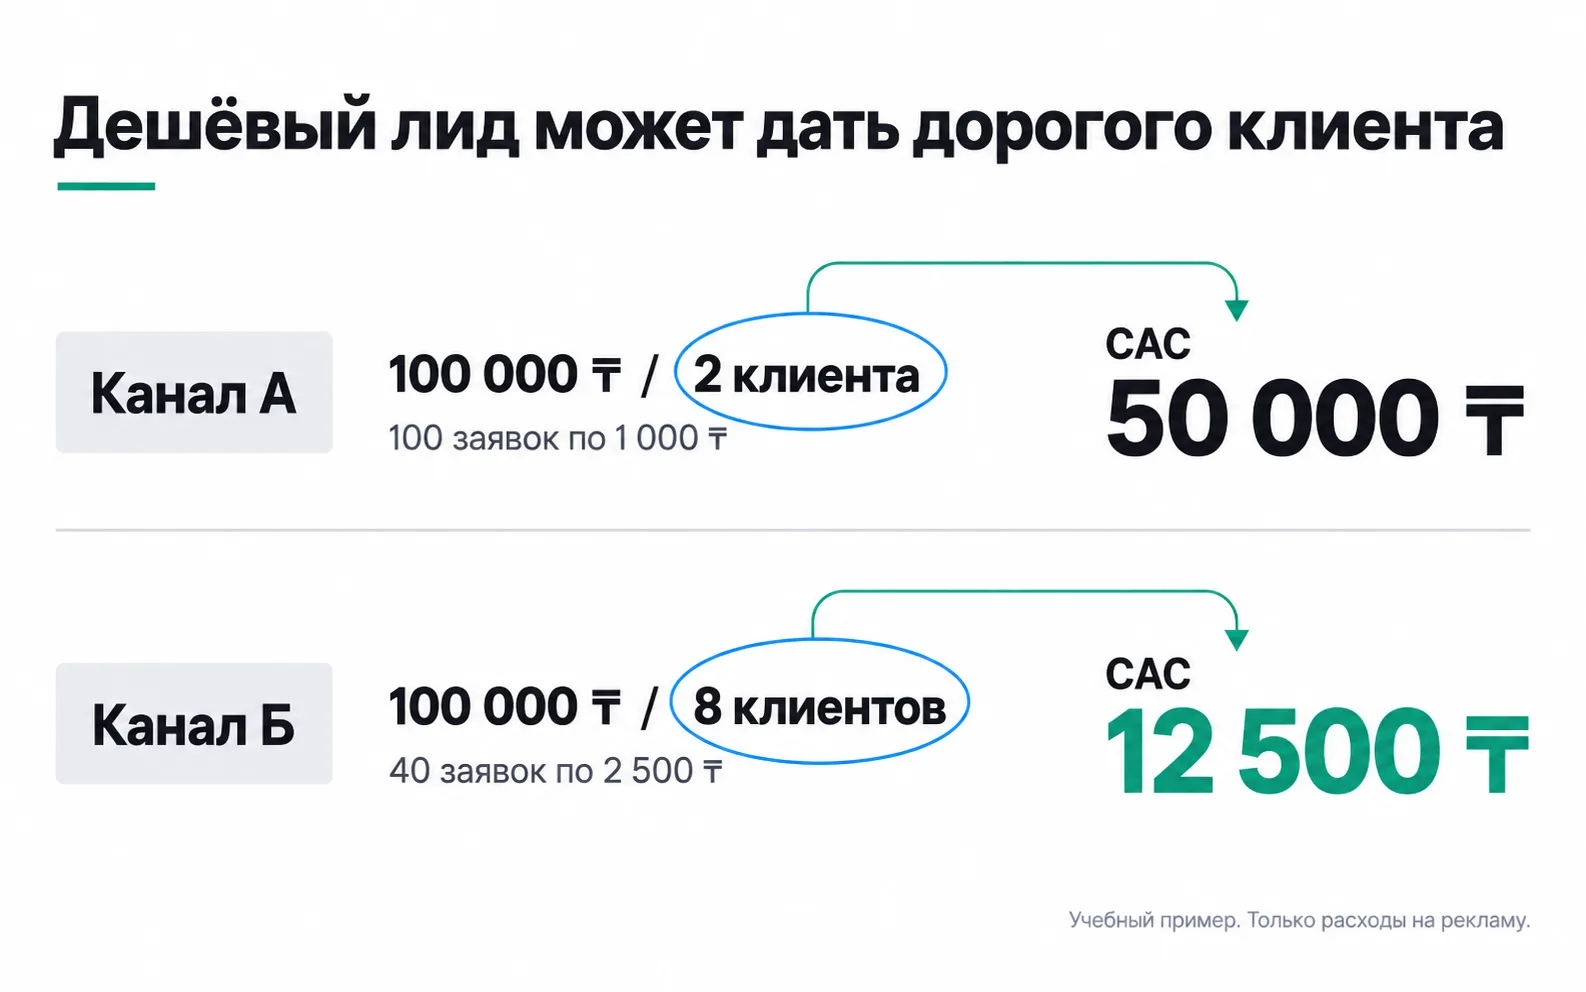
Two channels spend 100,000 ₸ each. The first brings 100 enquiries, the second 40. The marketer wants to move money to the first: its leads cost 1,000 ₸ instead of 2,500 ₸. But the CRM shows two new paying customers from the first channel and eight from the second. The owner needs both tables, or cheap enquiries will take budget away from cheaper sales.
Take an analytics reporting service for small retail chains. In our model, a client pays 60,000 ₸ per month, while preparing its report and providing support costs 20,000 ₸. All prices and figures in the example are made up. The image shows advertising spend and new customers, before other acquisition costs.
From an enquiry to a new customer
CPL divides spend by enquiries; CAC divides it by new customers. In this table, an enquiry is a unique contact from a company, and a customer is a company with its first confirmed payment. Two emails from one retail chain do not create two customers. A returning customer's payment also stays out of the CAC denominator.
| Metric | Channel A | Channel B |
|---|---|---|
| Advertising spend | 100,000 ₸ | 100,000 ₸ |
| Unique enquiries | 100 | 40 |
| New paying companies | 2 | 8 |
| CPL | 1,000 ₸ | 2,500 ₸ |
| Advertising CAC | 50,000 ₸ | 12,500 ₸ |
| Share of enquiries with a first payment | 2% | 20% |
B's higher lead cost is offset by the share that reaches payment. The cause is still unknown: the offer, audience, page or manager's work. Investigating it requires the enquiries and customer journeys. Calculating the financial result requires confirmed payments and the cost of serving those customers.
Compare spend and payments by cohort: customers acquired in the same month get the same time to pay. An enquiry on the last day of a month may pay the next month. Cohort CAC and the financial result for a calendar month may therefore draw on different rows. State the window and source alongside the figure so an unfinished cohort is not presented as final.
What remains from a sale
Of the 60,000 ₸ revenue per client, 20,000 ₸ goes to variable fulfilment costs: preparing the report and supporting that client. This leaves 40,000 ₸ of contribution before advertising and other expenses. The model has no discounts or refunds, and the amounts exclude indirect taxes; a real project follows rules agreed with finance.
| Calculation for new customers | Channel A | Channel B |
|---|---|---|
| First-month revenue | 120,000 ₸ | 480,000 ₸ |
| Variable fulfilment | 40,000 ₸ | 160,000 ₸ |
| Contribution before advertising | 80,000 ₸ | 320,000 ₸ |
| Advertising | 100,000 ₸ | 100,000 ₸ |
| Remainder after advertising | -20,000 ₸ | 220,000 ₸ |
A's first monthly payment did not cover acquisition. B has 220,000 ₸ left after the listed costs. The service still has fixed team pay, premises and shared tools, so the table's last row describes only part of the company's result.
It is easy to deduct a discount twice. If a client pays 54,000 ₸ instead of 60,000 ₸, revenue in the calculation is already 54,000 ₸. With fulfilment still costing 20,000 ₸, contribution is 34,000 ₸. There is no reason to subtract the 6,000 ₸ discount from that 34,000 ₸ again. Likewise, each commission belongs in one expense row.
Build the monthly P&L
A P&L, or profit and loss statement, shows income and expenses for a period. It reveals the result of the whole operation, including costs outside the advertising account. You can check financial terms in the SBA glossary, while the finance team agrees the rows in your own report.
In the closed month, the service delivered to and received payment from 20 companies: ten new clients from the two channels and ten returning clients. Each received the monthly package for 60,000 ₸. Contribution from all 20 enters the monthly result, but the new-customer advertising CAC denominator remains ten.
| Monthly row | Calculation | Amount |
|---|---|---|
| Revenue | 20 × 60,000 ₸ | 1,200,000 ₸ |
| Variable fulfilment | 20 × 20,000 ₸ | 400,000 ₸ |
| Contribution before marketing and fixed expenses | 1,200,000 - 400,000 | 800,000 ₸ |
| Advertising | Two channels at 100,000 ₸ | 200,000 ₸ |
| Other fixed expenses | Marketing, sales and management pay, premises, shared services | 400,000 ₸ |
| Result before tax | 800,000 - 200,000 - 400,000 | 200,000 ₸ |
The fixed 400,000 ₸ excludes advertising and the variable fulfilment already counted. This is a simplified model with no other expenses specified. A real P&L includes the company's remaining items; this remainder cannot simply be called net profit.
For fully loaded CAC, you can separately allocate part of fixed expenses to acquisition. Suppose 60,000 ₸ of marketing work and 40,000 ₸ of sales work from that same 400,000 ₸ are allocated to new customers. Fully loaded CAC for the cohort is (200,000 + 60,000 + 40,000) / 10 = 30,000 ₸ instead of the advertising-only 20,000 ₸. The P&L already includes that 100,000 ₸ inside fixed expenses, so it is not deducted again.
ROAS covers revenue and advertising only
Channel A's ROAS is 120,000 / 100,000 = 1.2. Revenue exceeds ad spend, but fulfilment leaves a negative 20,000 ₸. B's ROAS is 4.8 and its remainder is positive. ROAS and the remainder rank the channels the same way here only because both channels have the same price and contribution. Products with different costs will produce different results at the same ROAS.
With 40,000 ₸ contribution from 60,000 ₸ revenue, the contribution rate is two thirds. Covering advertising alone needs ROAS of 1.5: 100,000 / (40,000 / 60,000) = 150,000 ₸ in revenue. That threshold does not cover other expenses yet. If a channel needs a dedicated manager or expensive materials, include them in the decision calculation.
For ROMI, state the formula and cost scope: (incremental contribution before marketing - marketing costs) / marketing costs. Multiply by 100 if a percentage is required. Costs include the agreed campaign expenses, including preparation, rather than media placement alone. UTM tags or advertising attribution connect a sale to a touchpoint. Estimating how many sales the campaign added requires a separate comparison with a baseline without it, as in budget defence.
Profit and cash in the account
In our closed month, services were delivered and paid for. In the next launch, a client might pay later while advertising and contractors must be paid now. The P&L and cash schedule then describe different sides of the same work: whether the service earned money, and whether it has enough cash until payment arrives.
Prepayment needs care too. If a client pays for several months, some work is still ahead. Its cost cannot be forgotten just because the cash is already in the account. The company's financial policy sets revenue recognition by period; the marketer supplies order, payment and delivery dates.
Future repeat payments cannot be recorded as actuals either. Unit economics separates forecast contribution from what has already been earned. Channel A may pay back later if its clients stay, but that conclusion needs subsequent payments, not a habit of multiplying month one by twelve.
Exercise: calculate without double deduction
For your product, list the price after discounts, variable costs, advertising, other acquisition costs and fixed expenses. Reconcile paying customers by ID, separating new and returning customers. Label the P&L period and CAC window.
Now take a separate campaign for the same service: spend is 150,000 ₸, three new clients paid for and received their first month at 60,000 ₸ each, and fulfilment costs 20,000 ₸ per client. What are advertising CAC, ROAS and the remainder before fixed expenses?
CAC is 150,000 / 3 = 50,000 ₸. Revenue of 180,000 ₸ gives ROAS of 1.2. Fulfilment costs 60,000 ₸, leaving 120,000 ₸ contribution and a negative 30,000 ₸ after advertising. Later months may change the cohort's result, but the current row includes only services delivered and payments made under the agreed reporting method.
Video: the P&L
Compare the video's rows with your calculation and mark where campaign economics end and the whole company's result begins.