A marketer brings the owner a report: leads from channel A cost a third as much as leads from B. The owner is ready to move the budget, but the table does not show which leads paid or how much remained after fulfilling their orders. A decision requires connecting advertising to sales and costs.
The test contains 12 situations about customer needs, segments, offers, economics, retention and experiments. All companies and figures in this lesson's exercises are illustrative. Answer without hints first, then read the explanations, including those for options you did not select.
What the test result tells you
Each fully correct answer earns one point. When a question asks for several options, you must select every correct option and no incorrect ones. Partial answers receive no credit. There is no time limit or pass mark.
After finishing, you can retry questions you missed. Your first attempt remains saved, so you can see improvement after reviewing the explanations separately. A full restart replaces the saved answers and first result; the site asks you to confirm this first.
The test is available in Russian. The English page links to the Russian version. Answers are saved in this browser when local storage is available. They do not transfer automatically to another phone, and clearing site data may delete the attempt. If saving is blocked, a warning appears beneath the test.
A score of 12 out of 12 records your answers to these questions. Client work also requires a calculation with new data and an explanation of its limits. Academia does not issue a certificate or award a qualification based on the result.
Calculate customer cost after lead cost
After the test, take a separate example with two channels. Its figures differ from the question inside the test. Costs currently include only ad spend. The acquisition period and payment observation window are the same, and each lead and new customer is counted once. Repeat purchases do not add to the count of new customers.
| Measure | Channel A | Channel B |
|---|---|---|
| Ad spend | 100,000 ₸ | 150,000 ₸ |
| Leads | 100 | 50 |
| New paying customers | 5 | 10 |
| CPL | 1,000 ₸ | 3,000 ₸ |
| Ad spend per new customer | 20,000 ₸ | 15,000 ₸ |
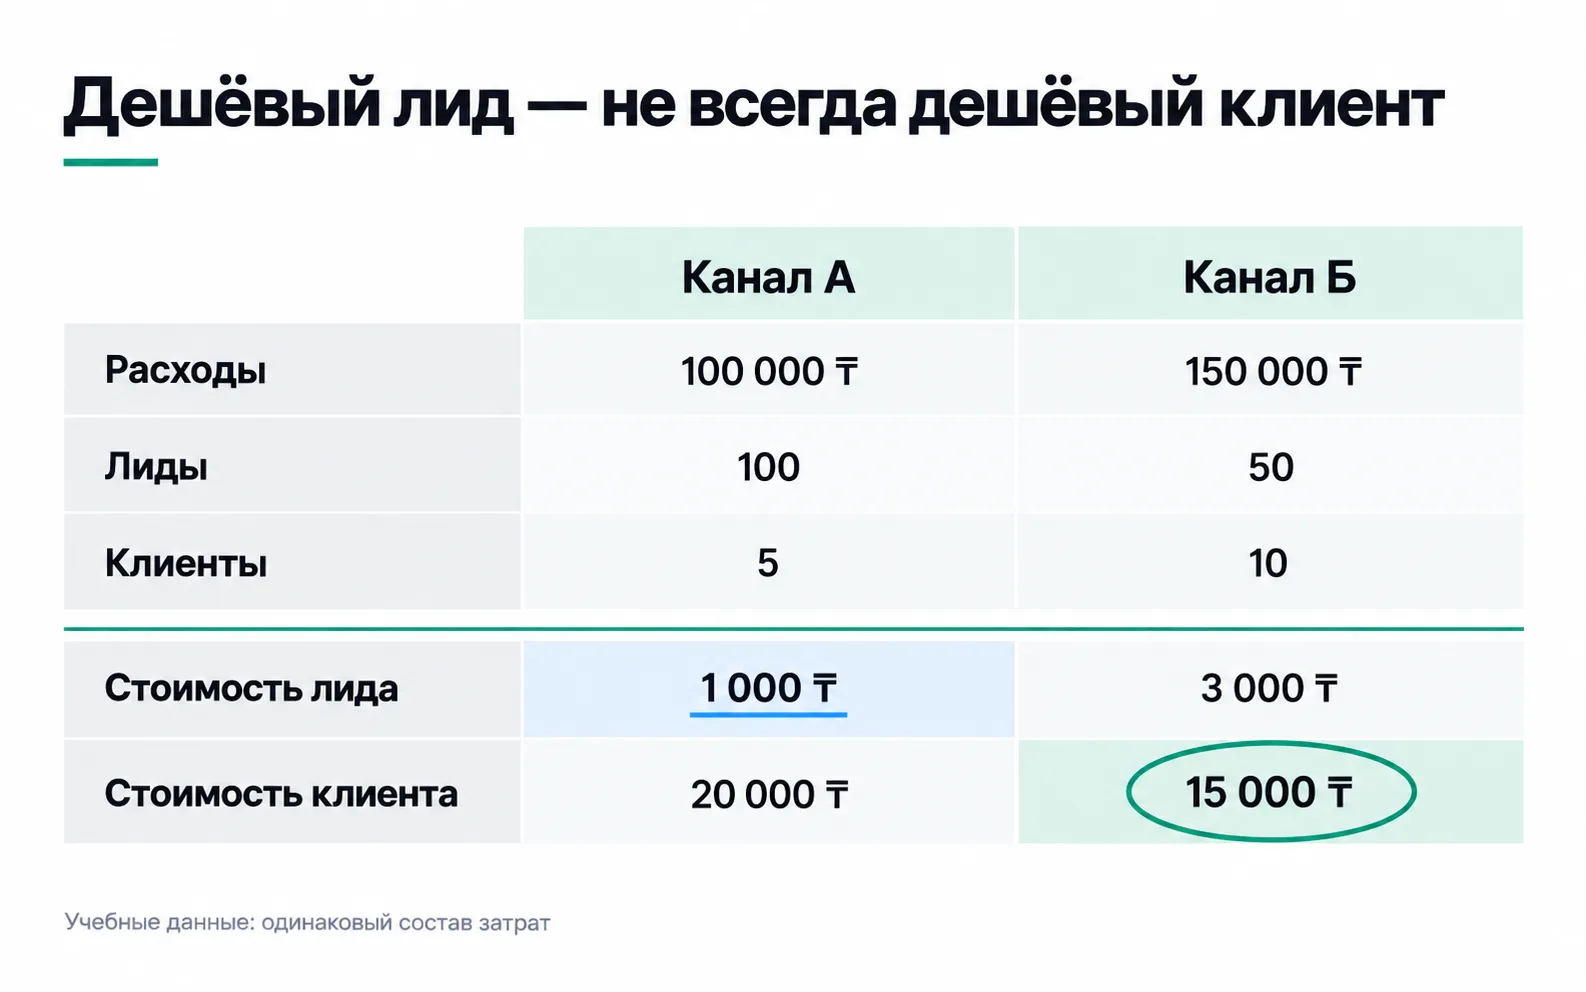
CPL divides spend by leads: 100,000 / 100 = 1,000 ₸ for A and 150,000 / 50 = 3,000 ₸ for B. On this measure, A looks more attractive. Yet only five of its hundred leads paid: 100,000 / 5 = 20,000 ₸ per customer. B produces 150,000 / 10 = 15,000 ₸. The more expensive lead resulted in a cheaper customer.
The illustration shows this calculation:
Full CAC requires an agreed scope for the other acquisition costs. Specialist work, ad production and handling new enquiries may cost different amounts in each channel. Until those figures are available, call the result ad spend per customer. This keeps the comparison clear and shows what the calculation still needs.
Compare order contribution
The owner asks, "So B will bring in more money?" Acquisition cost alone cannot answer that. Suppose customers from A buy a different set of products, leaving 30,000 ₸ each after variable fulfilment costs. Customers from B leave 12,000 ₸ each. These amounts already account for variable costs and returns within the chosen window, but exclude advertising and fixed costs.
A then contributes 5 × 30,000 - 100,000 = 50,000 ₸ after advertising. For B, the result is 10 × 12,000 - 150,000 = -30,000 ₸. Looking only at customer cost, we would have chosen B. With the stated contribution, we can see that its first orders did not even cover advertising. A has money left towards fixed costs; that balance is not yet net profit.
This additional information changes the decision because we now know more about customer economics. If customer value were equal, the comparison would look different. Future repeat orders can enter a separate scenario with a stated horizon and a basis for the forecast. They cannot count as money already earned.
Connecting the calculation to P&L produces a more precise answer for the owner: how much contribution was earned, which costs were deducted and what remains unknown. Lead volume serves as an intermediate result in that answer.
Justify the next allocation
Even A's positive contribution over the past period does not promise the same result after doubling its budget. The cost of the next customer, the audience mix or the workload for sales may change. If the team stops responding promptly, some new leads will not become paying customers.
Before expanding the budget, you need information on returns, repeat orders, payback time and fulfilment capacity. Five and ten customers provide little basis for a confident forecast of the next batch. Specify the additional spend you are prepared to test and the observation that would justify continuing or stopping. Set the test's size according to the business's risks and capacity.
If the report and CRM show different customer counts, align definitions and trace the records first. Reconciling analytics starts by asking what each system counted. Moving the budget beforehand may base the decision on an accounting difference.
Analyse your own mistake
Choose one question you got wrong or guessed. Write down which fact you overlooked, what you relied on instead and what additional condition might have made your answer reasonable. Then solve a similar problem with different figures and no multiple-choice answers.
If you chose A on CPL alone, the missing fact is straightforward: the share of leads who paid differs. But the rule "take the lower CAC" breaks too: with contributions of 30,000 and 12,000 ₸, A comes out ahead. A useful review explains which data determine the decision and lets someone repeat the calculation.
Exercise on your own project
Take two lead sources from your project over comparable periods. If you do not have a working project, use the figures above and prepare a separate table for a future client.
A colleague should be able to reproduce the completed calculation without a verbal explanation. If one source brought in later leads, give them a comparable payment window before comparing results. If variable costs are unknown, complete the customer-cost calculation and ask finance for the missing figures. An explicit gap is more useful than invented profitability.
For this lesson's example, the justified decision is more cautious than moving the entire budget: B's first orders do not yet cover ad spend, A provides a positive contribution before fixed costs, and the next allocation needs its own test. Your table may support a different conclusion. It should follow from your definitions, amounts and observations.